SBA 504 Loan 101: What is a “Debenture” and How Does it Work?
The SBA 504 loan is one of the available financing options for small businesses and entrepreneurs seeking long-term financing. Part of the funding for the SBA 504 loan is raised through a debenture issued to private investors. Even though the debenture is less flexible, meaning you have to pay the interest as agreed regardless of your performance, its low-interest rates make it a cost-effective method of securing funds for small businesses.
As long as you meet the Small Business Administration (SBA) requirements, you can benefit from the financing, expand your business, and supercharge your growth.
This article takes an in-depth look into the SBA 504 loan debenture to understand what it is, how it works, its eligibility requirements, and its benefits to small businesses. Let’s dive in.
What Is an SBA 504 Loan Debenture?
An SBA 504 loan is a facility designed for small businesses by the Small Business Administration (SBA) and funded partly by a Certified Development Company (CDC) and private investors (through debentures). The loan is usually long-term and takes a longer application process than other business loans; however, it has a lower interest rate than other forms of financing, making it more attractive for qualifying businesses.
A debenture is a debt instrument issued to raise money. In this case, the CDC gives the instrument to private lenders (large banks, insurance companies, pension funds, etc.) in exchange for 50% funding of the SBA 504 loan. The agreement outlines the loan amount, interest rate, and maturity date. After you pay the loan part of the interest goes to the private investors as interest income based on the debenture rate.
Small businesses acquire the SBA 504 loan mainly for major business expenditures such as purchasing buildings/real estate, machinery, equipment, etc.
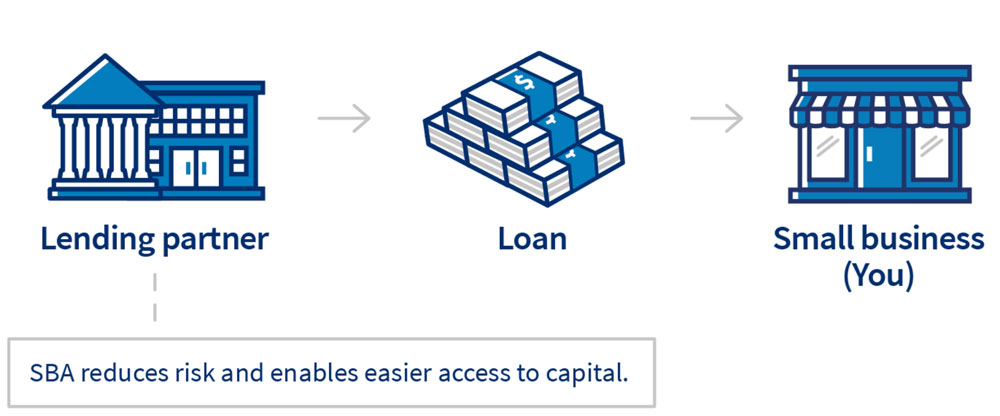
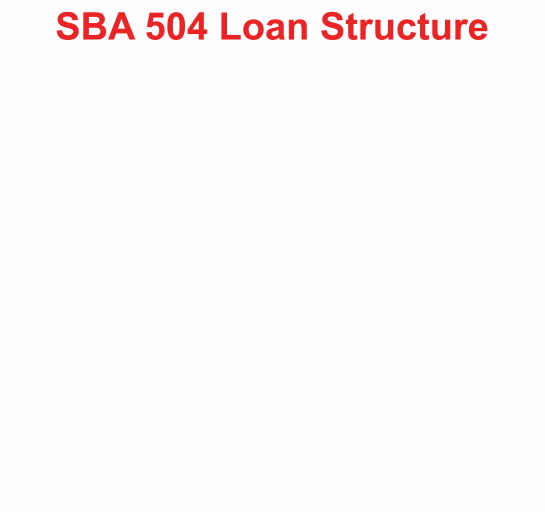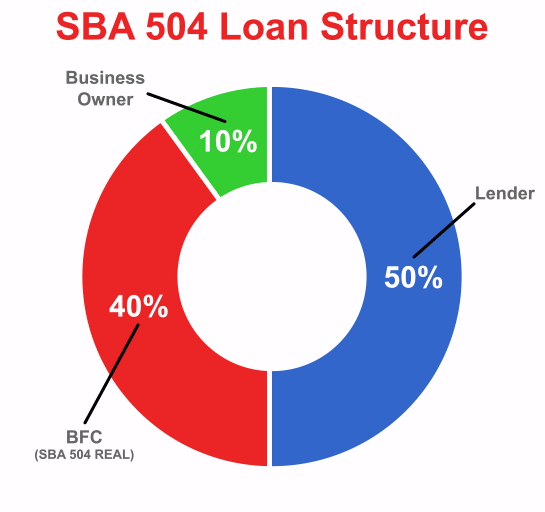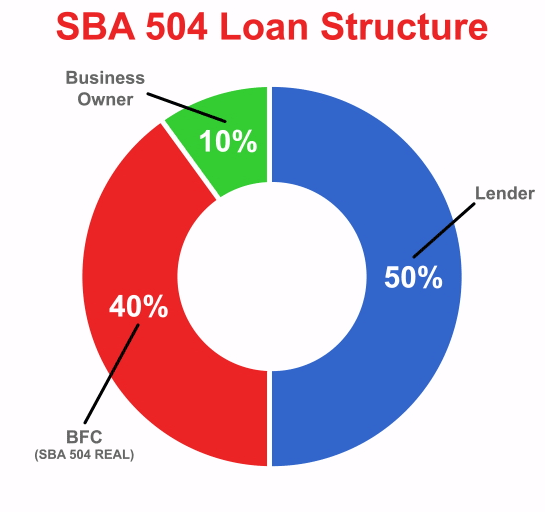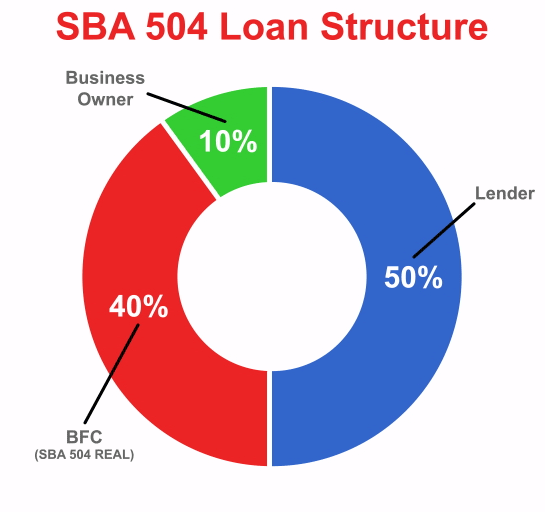
Certified Development Companies help you prepare the application and then they forward it to the SBA for approval. Upon approval, the SBA guarantees the loan but the CDC implements it by funding 40% while private investors buy 50% of the remaining loan through a debenture.
Though independent, Certified Development Companies are SBA certified non-profit organizations whose primary role is to help small businesses acquire 504 loans. However, some CDCs also assist applicants seeking 7(a) loans. While CDCs often work with banks that partially finance the businesses through debentures, CDC loan terms are generally more flexible than banks.
SBA 504 Loan Debenture Program Details and Requirements
As mentioned earlier, the SBA administers the program and guarantees the loans 100%. Businesses qualifying (check qualification requirements below) for the loan can apply through their chosen CDC and then wait for the SBA to approve the application and authorize funding.
The lenders earn their interest from the debenture, which they receive semi-annually. Though the interest is standardized across the lending institutions, the amount you pay may vary depending on the debenture term, which could be between 10 and 25 years.
In addition to facilitating the application and disbursing of funds, a CDC sets the guidelines for the loans advanced by the private lenders. The program is a win-win for businesses and lenders. Borrowers can access low-cost funding while the lenders get to advance funds more securely.
SBA 504 Loan Structure
Even though the loan is through the Small Business Administration (SBA), the funds do not come from the federal agency. The funding is split between a CDC, private investors (large banks, insurance companies, etc.), and the borrower (you) as follows:
- 50% – Private sector lender
- 40% – CDC
- 10% – Borrower
However, the 50-40-10 model may vary under different circumstances. For instance, if your company has been operating for less than two years, you may be obligated to provide a higher down payment of 15%, changing the structure to 50-35-15. In the same way, if your business is a special purpose property besides being less than two years in operation, you may pay 20% of the loan, resulting in a 50-30-20 model.
Debenture Loan Specifics
No matter how much funding your business needs, you are bound by the program requirements set by the SBA. These include:
Maximum Debenture Amount
The minimum debenture amount you can access through the program is $25,000, while the maximum is $5 million with a few exceptions who can receive up to $5.5 million (e.g., small manufacturers).
However, the amount you receive may be limited by how many jobs your venture has created. For instance, you must retain at least one job for every $65,000 advanced, but the manufacturers’ requirement is slightly lower at one job for every $100,000.
Maximum Debenture Percentage
The debenture finances 40% of the project. For instance, if the total project value is $500,000, the maximum debenture percentage can only be $200,000 (40% x $500,000).
Borrower’s Equity Requirements
The borrower’s equity requirement may vary depending on the circumstances. But the program finances up to 90% of the loan amount, meaning the borrower must provide at least 10% of the amount. However, the contribution does not necessarily have to be in cash. If you want the loan to construct a building on an already existing business property, the equity in the land could constitute your part of the contribution.
Use of Proceeds
SBA 504 loans must be used for specific purposes, including:
- Acquiring major assets (land, buildings, long-term machinery or equipment)
- Construction of new buildings or upgrading of existing facilities
- Some soft costs (architect fees, equipment delivery and setup, etc.)
Debenture Interest Rates
Interest rates vary from month to month. For instance, in May 2022, the rates were 4.922, 5.057, and 5.117 for 10, 20, and 25-year loans, respectively, a sharp variance from the same month in 2021, which were 2.612, 2.845, 2.933.
SBA 504 Loan Eligibility
To qualify for an SBA 504 loan, you must be a for-profit business with a net worth of not more than $15 million. In addition, your net income should not be more than $5 million after-tax for the past two years preceding the application date. You should also retain one job for each $65,000 advanced or $100,000 if you’re a small manufacturer.
Some businesses may not qualify for an SBA 504 loan despite meeting the above requirements, e.g., legal gambling businesses and pyramid schemes.
Summary of 504 SBA Loan Benefits for Small Businesses
The SBA 504 loan provides small businesses numerous benefits, both short-term and long-term. These include:
- Low-interest rates.
- Up to 90% financing.
- Your existing equity could be part of your 10% contribution, e.g., when acquiring a loan to build or upgrade a building on your current business premises.
- Longer loan amortization.
- Financing costs may be included in the loan.
Have questions about SBA 504 loans or want to apply for a SBA 504 loan? Call us at 1-800-SBA-REAL (722-7325) or submit a contact form and it’ll be our pleasure to help!
Business Financial Capital is Southern California’s leading SBA 504 loan Program expert, with over 20 years in the industry. We help California businesses grow by facilitating the premier tool for Real Estate financing—the SBA 504 loan.
Leave A Comment